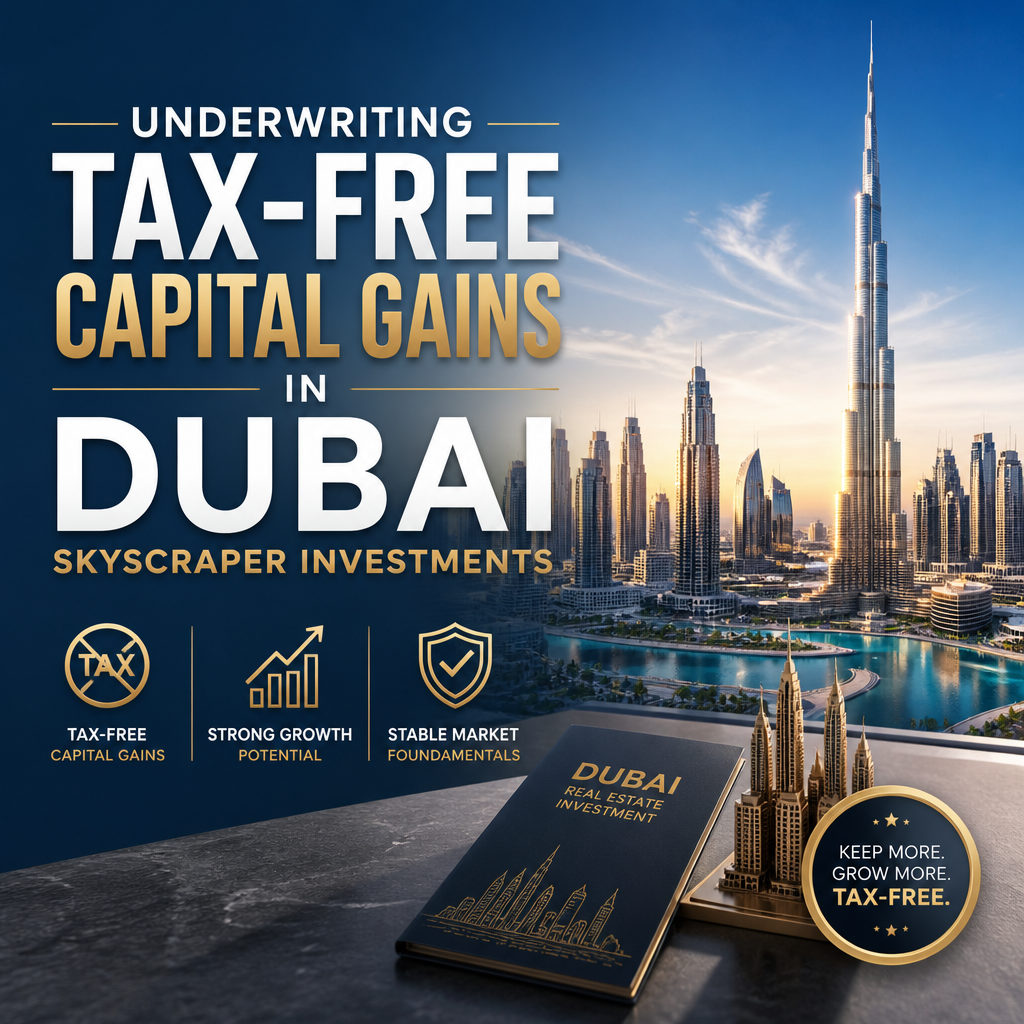
Underwriting Tax-Free Capital Gains in Dubai Skyscraper Investments
Underwriting Tax-Free Capital Gains: How Institutional Investors Approach Dubai Skyscrapers
Dubai’s skyscrapers have become more than symbols of ambition. They are increasingly viewed as institutional-grade assets, attracting sovereign wealth funds, private equity firms, real estate investment managers, and family offices from around the world.
For these investors, the appeal is not simply architectural prestige or strong tenant demand. The investment case often rests on a combination of rental income, capital appreciation, currency stability, infrastructure growth, and Dubai’s tax environment. Underwriting tax-free capital gains, however, requires a disciplined approach that goes well beyond assuming property prices will continue rising.
Why Dubai Skyscrapers Attract Institutional Capital
High-rise commercial and residential properties offer several characteristics that institutional investors value:
- Prime locations with limited developable land
- Access to major transport and business hubs
- Strong demand from international tenants and buyers
- Potential for long-term rental growth
- Liquidity relative to smaller or less established markets
- Global visibility and brand value
Buildings in areas such as Downtown Dubai, Dubai Marina, Business Bay, and the Dubai International Financial Centre can benefit from proximity to employment centers, luxury retail, hospitality, and public transportation.
Yet institutional investors rarely underwrite an entire market based on headline growth. They evaluate each tower as a distinct operating business, with its own tenant profile, service costs, lease structure, physical condition, and competitive position.
Understanding the Tax Advantage
The United Arab Emirates generally does not impose personal income tax, and qualifying real estate capital gains are not typically subject to a separate personal capital gains tax. This can improve an investor’s potential net return compared with markets where appreciation is taxed directly.
However, “tax-free” does not mean “risk-free” or universally exempt from all obligations. Institutional underwriting considers:
- Corporate tax treatment
- Value-added tax implications
- Withholding and transfer-related costs
- Ownership structure
- Financing arrangements
- Jurisdiction of the investing entity
- Applicable regulations in the investor’s home country
Tax assumptions must therefore be verified with legal and tax advisers. A change in regulation, a different holding structure, or international tax rules can materially affect the final return.
Building the Underwriting Model
Institutional investors typically model a skyscraper across multiple scenarios rather than relying on a single forecast. The model may include acquisition costs, financing, operating expenses, rental income, vacancy, capital expenditure, refinancing, and exit proceeds.
Revenue Assumptions
Revenue forecasting begins with the property’s current rent roll. Analysts review:
- Contracted rents and lease expirations
- Occupancy and tenant retention
- Rent-free periods and incentives
- Service charge recovery
- Tenant concentration
- Exposure to short-term or flexible leasing
For residential towers, assumptions may also include furnished versus unfurnished units, seasonal demand, management fees, and the relationship between sale prices and rental yields.
A conservative model distinguishes between achieved rents and advertised rents. It also tests whether future growth is supported by real demand or merely by temporary supply shortages.
Operating Costs and Capital Expenditure
Luxury towers can generate strong revenue while carrying significant expenses. Cooling, security, elevators, façade maintenance, amenities, insurance, and common-area management can all affect net operating income.
Institutional investors also reserve funds for major capital expenditure, such as:
- Mechanical and electrical system upgrades
- Façade restoration
- Lobby and amenity refurbishment
- Elevator modernization
- Energy-efficiency improvements
- Compliance and safety works
Underestimating these costs can inflate projected returns and create unpleasant surprises during ownership.
Stress-Testing Capital Appreciation
The central question is not whether Dubai skyscrapers can appreciate, but whether the investment remains viable if appreciation is slower than expected.
Investors may test scenarios involving:
- Higher interest rates
- Lower rental growth
- Increased vacancy
- New competing towers
- Declining transaction liquidity
- Construction delays
- Weaker expatriate demand
- A longer holding period
A strong investment case should not depend entirely on selling at a premium. Ideally, operating income provides a reasonable foundation while capital growth supplies additional upside.
Exit assumptions are equally important. Institutional investors examine likely buyers, comparable transactions, unit liquidity, building quality, and the timing of the sale. A landmark address may attract attention, but marketability still depends on pricing and asset fundamentals.
Location, Quality, and Liquidity
In Dubai, location is closely linked to infrastructure and connectivity. Access to metro stations, major roads, airports, waterfronts, employment clusters, and lifestyle amenities can support both occupancy and resale demand.
Building quality matters just as much. Institutional buyers assess the developer’s track record, construction standards, facilities management, owners’ association governance, and maintenance history.
Liquidity can vary significantly between towers. A property with a broad base of potential buyers may be easier to exit than a highly specialized asset, even if both are located in the same district.
A Disciplined Approach to Risk
Underwriting tax-free capital gains in Dubai requires more than projecting rising prices. It demands a detailed assessment of income durability, operating costs, regulatory exposure, financing risk, and exit liquidity.
The most credible investment thesis combines tax efficiency with genuine asset quality. For institutional investors, the winning skyscraper is not necessarily the tallest or most famous. It is the building that can preserve occupancy, generate dependable cash flow, withstand market stress, and retain buyer appeal across the investment cycle.
